Illinois Moves to Cap Consumer Loan Interest Rates, Lenders Subject to Penalties and Other Relief
On January 13th, the last day of the Illinois legislature's six-day lame duck session, the General Assembly passed the Illinois Predatory Loan Prevention Act (PLPA) as part of SB 1792.
The PLPA caps consumer loan annual percentage rates at 36% for both open and closed end credit. The 36% APR should be calculated using the system of calculating a military annual percentage rate under federal law, which is widely considered an "all-in" method of calculating rates and fees. The Illinois Department of Financial and Professional Regulation (IDFPR) may issue rules pertaining to the Act.
The General Assembly has 30 days to send the bill to the governor, and the governor has 60 days to sign it. The bill is widely expected to be signed by the governor, making the last possible effective date March 23, 2021. The rate cap will be imposed on all loans made on or after the effective date.
Loans that violate the Act are considered void and uncollectable. In addition, IDFPR may issue a cease and desist letter and a $10,000 fine against lenders violating the Act. Violations of the Act constitute violations of the Illinois Consumer Fraud and Deceptive Business Practices Act, thereby increasing penalties and other relief.
Lender is broadly defined as anyone that participates in offering, arranging or making a loan, or that holds an interest in a loan. The Act expressly covers transactions that are a disguised loan, or a subterfuge for the purpose of avoiding the PLPA. Banks, savings banks, savings and loan associations, and credit unions are exempt.
Industries that will be most affected include those licensed under the Consumer Installment Loan Act, Payday Loan Reform Act, Sales Finance Agency Act, Motor Vehicle Retail Installment Sales Act, and the Retail Installment Sales Act.
The PLPA was included as part of a larger, comprehensive legislative package introduced and championed by the Black Caucus to bring reform in these four core areas:
- Education and Workforce Development Omnibus (HB 2170; Passed Both Chambers)
- Criminal Justice Reform Omnibus (HB 3653; Passed Both Chambers)
- Economic Equity (Every bill Passed Both Chambers)
- Health Care and Human Services Reform (SB 558 and HB 3840; each bill failed to get a concurrence vote before session ended).
Lenders and other entities potentially affected by the 36% rate cap should begin implementing compliance and controls immediately.
Featured Insights
Press Release
Sep 22, 2026
Vaishali Rao Selected as a Global 2026 INvolve Heroes Role Model
Consumer Crossroads: Where Financial Services and Litigation Intersect
Sep 22, 2026
Another Court Finds the TCPA Does Not Apply to Texts —Time for Supreme Court Intervention?
Press Release
Sep 22, 2026
Min Kang Appointed to the Washington State Bar Association Board of Governors
Press Release
Sep 22, 2026
Vaishali Rao Selected as a Global 2026 INvolve Heroes Role Model
Consumer Crossroads: Where Financial Services and Litigation Intersect
Sep 22, 2026
Another Court Finds the TCPA Does Not Apply to Texts —Time for Supreme Court Intervention?
Press Release
Sep 22, 2026
Min Kang Appointed to the Washington State Bar Association Board of Governors
In The News
Sep 22, 2026
Spencer Kook Analyzes California's Liability Influence in the National Insurance Market
In The News
Sep 21, 2026
Marisa Roman Cautions Clickwrap Agreements Are Not Enough to Let Companies Off “Scot-Free”
Press Release
Sep 18, 2026
Paris Glazer Named to Chicago Daily Law Bulletin’s 2026 40 Attorneys Under Forty
Consumer Crossroads: Where Financial Services and Litigation Intersect
Sep 17, 2026
Federal and State Regulators Continue Crackdown on Junk Fees
Press Release
Sep 17, 2026
Defense Verdict Reduces $134 Million Demand to $2 Million in Catastrophic Motorcycle Injury Case
Insights for Insurers Alert
Sep 16, 2026
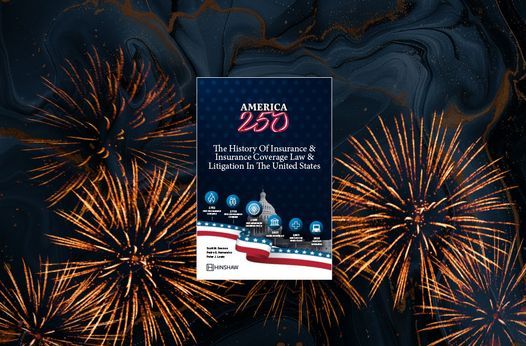
America 250: The Nation’s Unique Contributions to Insurance Coverage Law and Litigation
In The News
Sep 15, 2026
Lucy Wang Discusses the California Insurance Commissioner’s Role in Protecting Consumers
Press Release
Sep 10, 2026
Hinshaw Attorneys Recognized as 2027 Lexology Index Thought Leaders: USA
In The News
Sep 10, 2026
Nicholas Ajello and Gregory Emry Analyze FAA’s Proposed BVLOS Drone Regulations